Improving Your Credit Score for Home Buying
Real Estate Jade Knight March 18, 2024
Real Estate Jade Knight March 18, 2024
A strong credit score is extremely helpful when applying for a mortgage. If you’re planning to buy a house soon, you might wonder if your credit score is good enough to be approved for a home loan. Fortunately, there are several steps you can take to increase your credit score before you purchase a home.
Your credit score doesn’t need to be perfect to purchase a home, but a higher score will earn you a lower interest rate. The median credit score for buyers taking out a mortgage is 770. However, the minimum credit score to be approved for a conventional mortgage is 620. If you’re applying for an FHA loan, you’ll need a credit score of 580. If your score is between 500 and 580, you may be approved for an FHA mortgage with a 10% down payment.
Increasing your credit score is one of the best things you can do as you prepare to purchase a home. A good credit score shows your mortgage lender that you’re a trustworthy borrower. When you have a long and diverse credit history, a record of making payments on time, and low credit utilization, your lender has confidence that you’ll repay your home loan. Because they’re taking on less risk, they can offer you a lower interest rate.
Your interest rate has a massive impact on your monthly payments. One percentage point could make a difference of hundreds of dollars per month. Over the lifespan of the loan, this could amount to tens of thousands of dollars. Securing a lower rate will save you money or allow you to buy a home at a higher price.
Your credit score can also be a reflection of your overall financial situation. When you work to improve your credit, you’re probably paying off debt and keeping your finances highly organized. By building these good habits, you set yourself up for success with your mortgage.
Some elements of your credit score may be outside of your control. For example, late or missed payments can stay on your report for seven years. If you missed a payment on a loan, your only option may be to wait for that derogatory mark to fall off the credit report. However, there are several steps you can take to increase your score as you prepare to buy a home. Here are seven tips for improving your credit:
Increasing your credit score takes time, so the earlier you can start, the better. Even if you don’t plan on buying a home for many years, working on your credit now will pay off when you eventually apply for a mortgage. It’s also important to remain patient throughout the process. You might not be able to make drastic changes to your credit score overnight, but staying consistent with your payments over the course of months or years will make a difference.
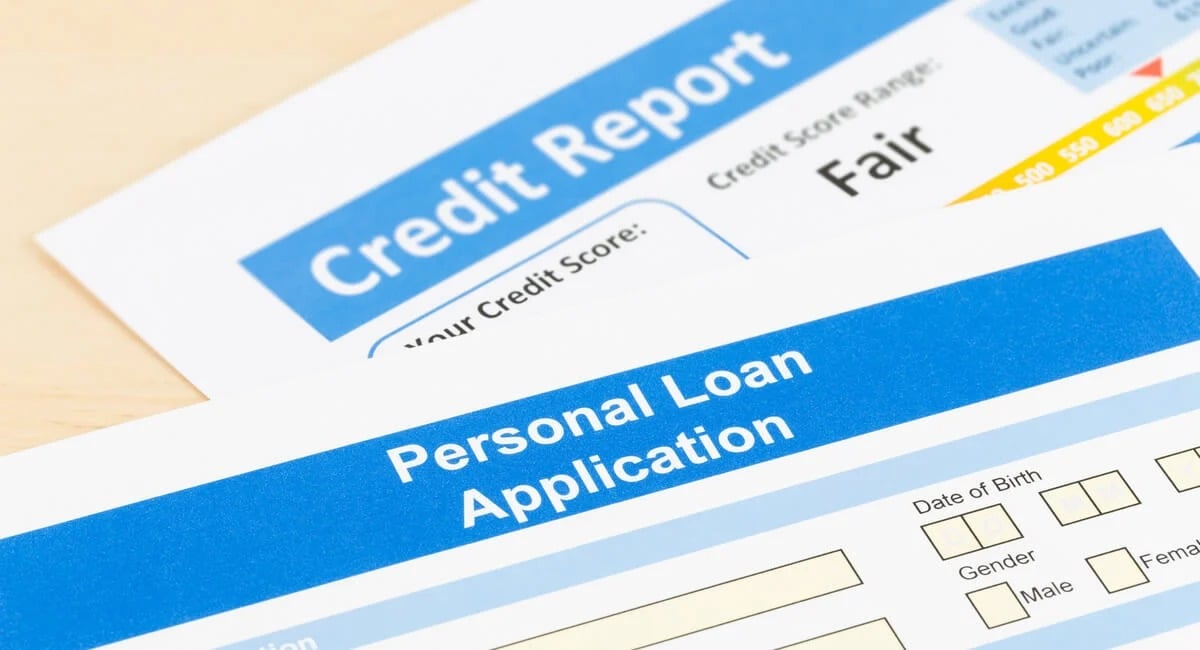
To create a successful plan for increasing your credit score, you need to review your credit report. You can get a free copy of your report from TransUnion, Equifax, and Experian every year. Apps like Credit Karma can also help you better understand your credit score.
Your score is calculated based on several factors, including the length of your credit history, your total credit utilization, the number of open accounts, the number of hard inquiries, and the number of derogatory marks. Reviewing this information will help you identify weaknesses in your credit report. For example, if you have a lot of hard inquiries, you should avoid applying for new loans or undergoing any more credit checks. If your credit utilization is high, you should focus on paying down your credit cards.
Sometimes, lenders mistakenly report missing or late payments to the credit bureaus. This is another reason that carefully reviewing your credit report is so important. One derogatory mark can have a significant impact on your score, so correcting any mistakes that you notice on your report is key. You can contact the credit bureau directly by phone, mail, or through their website. Be prepared to explain why you’re disputing the remark and to provide any documents you have that support your claim. For example, you could provide a bank statement that confirms you made a payment that’s reported as missing.
Your credit utilization, or the percentage of your total available credit that you’re currently using, is one of the biggest factors in determining your score. Paying down debt is one of the best ways to boost your credit score and get approved for a mortgage.
Everyone’s financial situation is different, but it’s generally wise to focus on paying off credit card debt first. The lower your credit card balances, the lower your total credit utilization. Credit cards also tend to have higher interest rates than most other loans, so paying them off as quickly as possible will save you a lot of money in interest. You could also ask your credit card provider for an increase to your credit limit. Then, your current balance will become a smaller percentage of your total available credit.
Paying off other debts, such as car loans or student loans, can increase your credit score as well. Additionally, when applying for a mortgage, your lender will calculate your debt-to-income ratio. Having less total debt will increase your chances of being approved for a home loan.
Paying all of your bills and loans on time is vital when you’re preparing to buy a home. Derogatory marks stay on your credit report for years, so one missed payment can be a costly mistake. If you struggle to make your payments on time, consider enrolling in auto-pay or setting reminders on your phone. Most lenders won’t report a missing payment until it’s 30 days late, but you should never risk it.
Having more open accounts is typically better for your credit score. Although it may be tempting to close a credit card once you’ve paid it off, it’s actually better for your score to keep the account open. The length of your credit history matters, too. Credit bureaus consider the average age of your accounts when calculating your score. Closing an old account could shorten your credit history, which will negatively impact your score.
Even though having a variety of open accounts is good for your credit score, you should avoid opening new accounts if you’re planning to buy a home soon. Whenever you apply for a loan, your lender will conduct a credit check, which will reduce your credit score. Mortgage lenders also prefer that you keep your finances consistent while applying for a home loan. They may be more likely to decline your application if you’ve recently taken on a lot of debt.
Boosting your credit score may seem like an intimidating process, but your score is made up of many factors that are mostly within your control. After reviewing your credit report, choose a few areas to focus your energy and attention on. If you’re committed and thoughtful in your approach, you can make a big difference before you apply for a mortgage.
Stay up to date on the latest real estate trends.
Which is why any time a bank ends up taking possession of a home by means of a foreclosure.
If you absolutely must buy a home before you sell yours, you should at the very least do the following.
Sinking funds allow you to save up gradually for bills that you know will arrive in the future.
So if you wish to hold an open house, make sure you host an agent and broker only open house.
Financing
Funding Your Dream Home Renovations - HILLTOP Team
Real Estate
Buying a house with your partner is an incredibly exciting prospect, but it’s also a huge commitment.
When buying a home, the down payment and the monthly mortgage are only the beginning of your expenses.
Real Estate
The vast majority of millennial home buyers, especially young millennials, are first-time buyers.
In addition to all of the economic and practical reasons for purchasing a single-story home.